The shareholder who sold
what he did not own
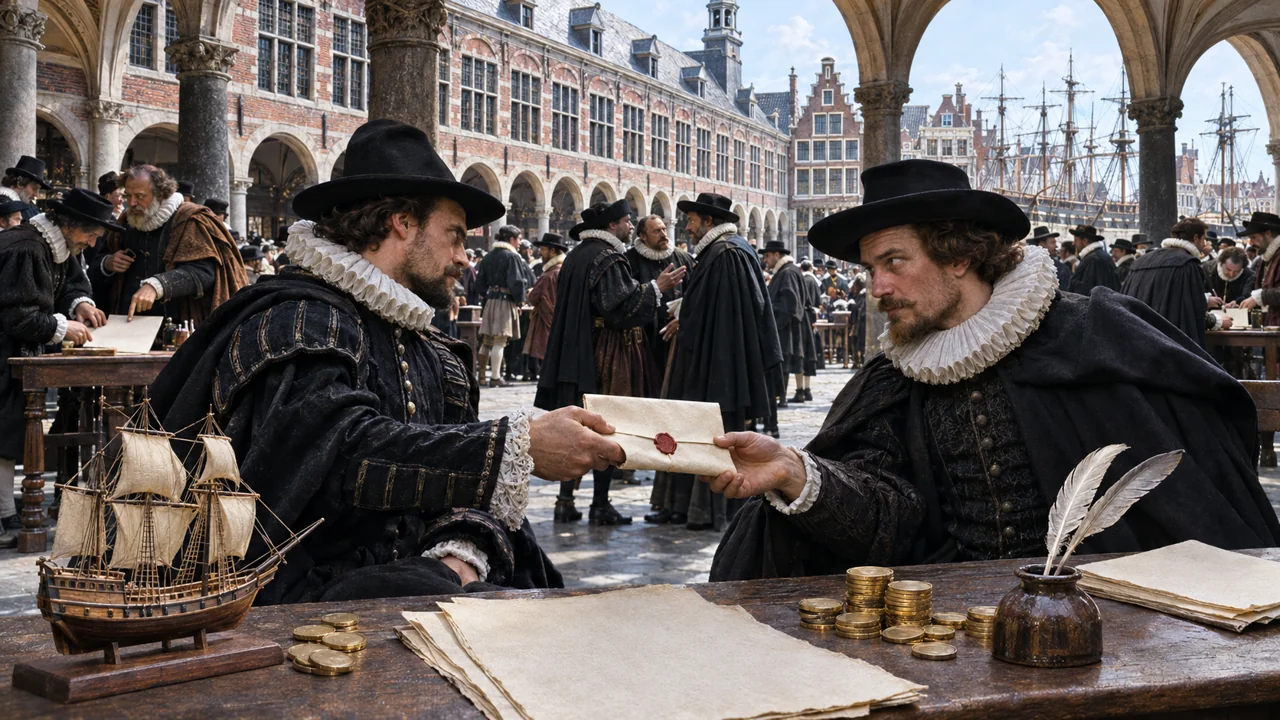
In 1609, a former director of the Dutch East India Company sold shares he did not own, hoping to push their price down. The following year the authorities banned the practice: it is one of the first laws ever devoted to share trading.
A bet against his own company
Isaac Le Maire was among the first large shareholders of the Dutch East India Company (VOC), founded in 1602 and whose shares changed hands in Amsterdam. Pushed out of its management in 1605 after a dispute, he judged that the company spent too much on equipping its ships and too little on rewarding its shareholders. His plan for a rival company was refused: the VOC monopoly stood.
In 1609 he joined other investors in the Groote Compagnie, often likened to a hedge fund. The mechanism is simple. One sells shares one does not hold, forward, at today's price, to buy them back later for less and pocket the difference. According to several accounts, rumours of ships lost on the voyage home from Asia accompanied the operation, to help the price slip.
Historians at the Amsterdam stock exchange museum note that the operation was meant to earn money, but above all to weigh on the VOC share price. Short-selling the company you were pushed out of turns the market into an instrument of reprisal.
The company and the authorities reacted. In 1610 a proclamation of the States General prohibited speculation on a fall in VOC shares, that is, selling securities one does not yet own. On the evidence available, it is the first law devoted to share trading.
A market learning that it needs rules
From the outset the episode raised a question that stock exchanges have never left behind: is short selling a tool of information or a weapon? Its defenders see a way for prices to absorb bad news and for markets to stay liquid. Its critics see a lever for manipulation, especially when paired with rumours.
Every financial storm revives the debate. In September 2008 the United States temporarily suspended short selling in many financial stocks; in spring 2020 several European countries did the same. The distinction worth keeping is the one between speculating on a fall and causing it. The 1610 law does not settle the first question, but it shows that a market in securities needs referees very early on.
Betting on a company's fall is one thing; deciding to hasten it is another, and that is where the rule begins.