The Mississippi
Bubble
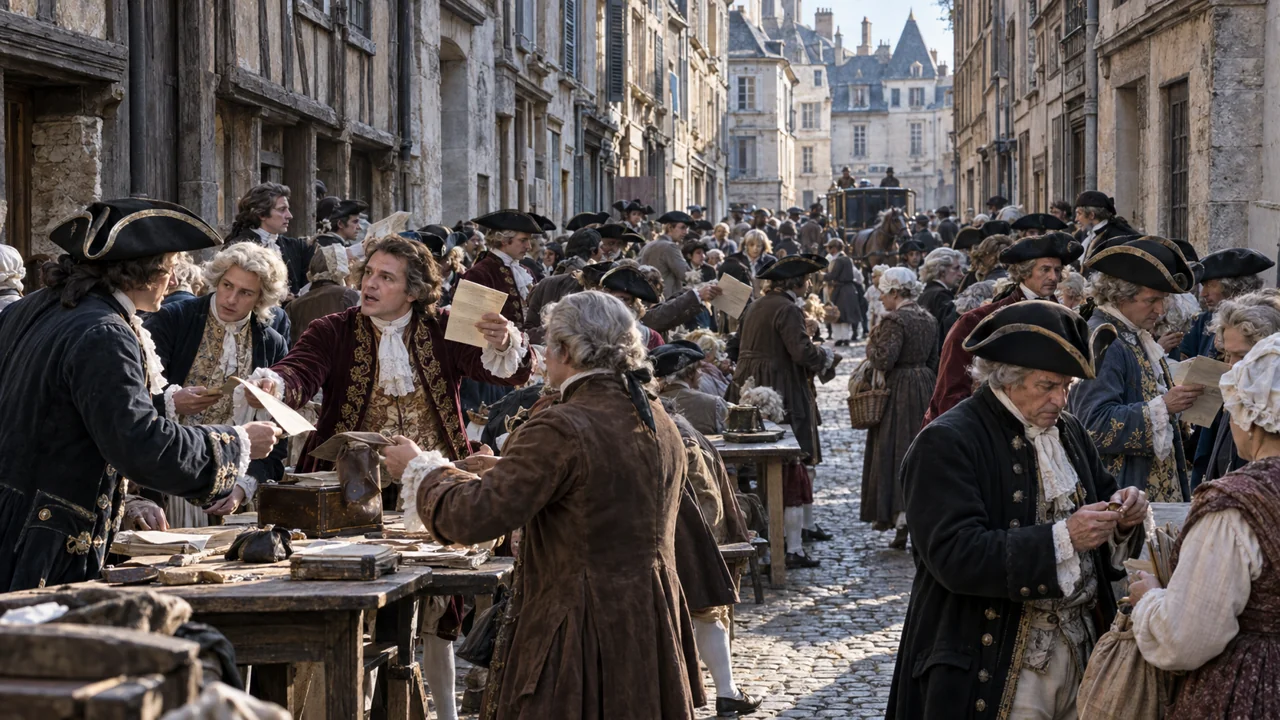
In 1720 crowds packed the rue Quincampoix in Paris to buy shares in a company holding the Louisiana monopoly. Within months John Law's paper made fortunes, then unmade them.
From banknote to share frenzy
In 1716 the Scotsman John Law opened the Banque Générale in Paris, which issued banknotes. France emerged from Louis XIV's reign with a debt of about 2.8 billion livres, and the Regent lent an ear to a financier offering to settle it with paper. Law went on to found the Compagnie d'Occident, holder of the Louisiana trade, which in 1719 he enlarged by absorbing rival companies into the Compagnie des Indes.
The share, near 500 livres in spring 1719, reached 1,000 livres on 21 July and 3,000 on 17 August; at its peak it came close to 10,000 livres. On 5 January 1720 Law became Controller-General of Finances, and in February the bank, now royal, was absorbed by the company. The rue Quincampoix, a narrow street, served as an improvised exchange.
The mechanism was circular: the company issued shares payable in banknotes, the bank printed the notes that propped up the price, and a high price justified new issues. The money supply nearly doubled, and inflation reached 23% a month in January 1720.
Money backed by a promise
On 21 May 1720 Law tried to deflate the bubble through a scheduled cut in the value of banknotes and shares. The measure was reversed six days later, but confidence was broken, and he lost his post on 29 May. The share fell to about 2,000 livres in September, 1,000 in December and 500 by September 1721. Law left France for Brussels on 22 December 1720 and died in Venice in 1729.
The System mixed a sound intuition, that paper money can support economic activity, with a fatal confusion that tied share prices to colonial profits still to come. Today's debates carry its trace: central banks financing public debt, assets priced on a story. Historians often cite the System's failure among the causes of France's lasting distrust of issuing banks.
A bubble is measured not by the price it reaches but by the promises that must still be issued to hold it up.