The hundred-trillion note
that was worth thirty dollars
On 16 January 2009, Zimbabwe's central bank put into circulation a note worth one hundred trillion Zimbabwe dollars. On the day it was issued it was worth about thirty US dollars; three months later, the currency that printed it was abandoned.
Zeros struck out faster than they could be printed
In the early 2000s the Zimbabwean state was financing its spending by printing money while the country's output collapsed. Prices followed the printing press. The Reserve Bank of Zimbabwe first tried to hide the runaway by removing zeros: three in 2006, ten in 2008 and twelve in February 2009, twenty-five in all. Each time, the new money lost its value within weeks.
In November 2008, according to economist Steve Hanke's estimates, prices were doubling every 24.7 hours, a pace that puts Zimbabwe second among recorded hyperinflations, behind Hungary in 1946. The notes swelled with prices: ten, twenty, fifty and then one hundred trillion Zimbabwe dollars, all issued on 16 January 2009.
Once the currency was abandoned, the central bank kept the notes redeemable until 30 September 2015; by June 2015 a note of one hundred trillion was worth only forty US cents, less than collectors were offering for it. Meanwhile Zimbabweans had turned to foreign money: in January 2009 use of the US dollar, the euro and the South African rand was officially allowed, and on 12 April 2009 the unity government suspended the national currency.
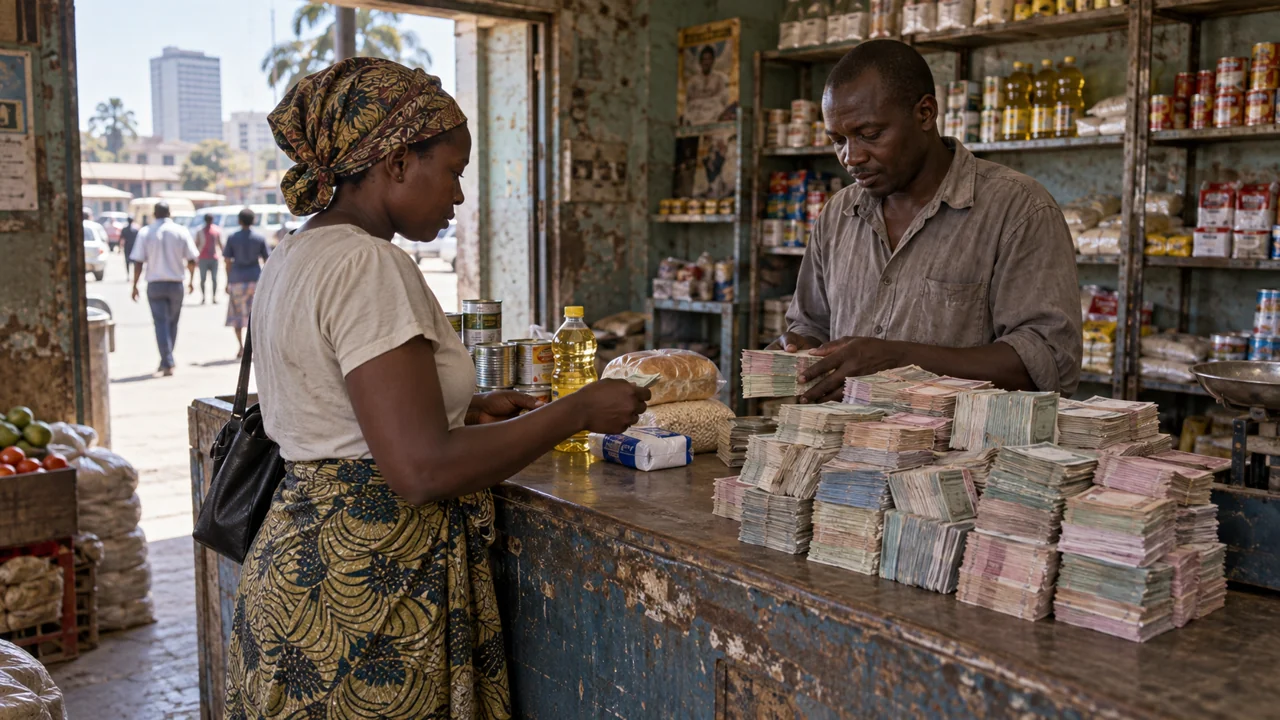
A currency is worth only the rule that limits its issue
Zimbabwe is the extreme laboratory of a mechanism that economist Philip Cagan described as early as 1956: beyond a rise in prices of about 50% a month, money enters hyperinflation. Everyone tries to get rid of it before it loses more, which speeds up the rise and keeps the circle turning.
The episode also shows what a currency owes to something other than the state that issues it. The power to print has no physical limit; its only limit is users' confidence, which withdraws all at once. Zimbabweans did what Gresham's law would predict: they kept the more reliable foreign currencies and shunned their own. The lesson lights up today's debates on monetary discipline, central bank independence and dollarization: what holds a currency up is less the banknote than the rule that limits its issue.
A currency does not die for want of banknotes, but for want of a reason to believe in it.